

Suppose you are buying at a $400,000 loan amount. A 6.50% rate gives a principal-and-interest payment of about $2,528 a month, while 6.25% gives about $2,463. That $65 monthly gap adds up to roughly $3,900 over five years, which is why how you shop matters as much as what you submit. This guide is for buyers who want their documents ready and their options clear. The tools below were judged on checklist and document upload support, how credit is pulled, loan program fit, and how plainly each explains next steps. By Duane Buziak, NMLS #1110647.
Jump to a Section
- Quick comparison
- The documents and rules behind every pre-approval
- 1. Grand Rates by Duane Buziak
- 2. Rocket
- 3. Veterans United
- 4. Movement
- 5. Guild Mortgage
- 6. NFM Lending
- Ten questions buyers ask about pre-approval
- Matching a Pre-Approval Tool to Your Situation
Quick Comparison
- Grand Rates by Duane Buziak: ideal for buyers who want independent guidance before committing; free to the borrower; compares pricing across hundreds of wholesale lenders before any hard credit pull.
- Rocket: ideal for buyers who want a fast, fully online approval; no upfront cost to apply; the most app-driven pre-approval workflow on the list.
- Veterans United: ideal for veterans and service members using a VA loan; pricing on its website; built-in support for eligibility paperwork.
- Movement: ideal for buyers who want a loan officer plus online convenience; pricing on its website; a loan officer-led process paired with digital intake.
- Guild Mortgage: ideal for buyers who prefer face-to-face help; pricing on its website; a local branch network.
- NFM Lending: ideal for buyers who want one dedicated loan officer; pricing on its website; a relationship-driven process.
| Tool | Model | Compares across lenders | Main way you work with it | Narrowest fit |
|---|---|---|---|---|
| Grand Rates by Duane Buziak | Independent consultation | Yes, wholesale lender network | Consultation and document coaching | Licensed in VA, FL, TN, GA, DC, NC, SC, MD |
| Rocket | Single lender | No | Online application and upload | Less hands-on support |
| Veterans United | Single lender, VA focus | No | Online portal plus loan team | VA-eligible buyers |
| Movement | Single lender | No | Loan officer plus portal | No independent comparison |
| Guild Mortgage | Single lender, branches | No | Local officer plus digital tools | Varies by branch and state |
| NFM Lending | Single lender | No | Dedicated loan officer | Confirm state availability |
The Documents and Rules Behind Every Pre-Approval
Pre-qualification is a quick estimate based on what you tell a lender. Pre-approval is a closer review: you submit documents, the lender verifies them, and a credit report is pulled. Neither is a loan commitment. Final approval still depends on the appraisal, title work, and unchanged finances through closing.
Most lenders ask for the same core set:
- Government-issued photo ID and Social Security number
- Two years of W-2s and federal tax returns (self-employed buyers usually add business returns and a year-to-date profit and loss statement)
- About 30 days of recent pay stubs
- Two months of bank and asset statements, all pages
- Employment history and a list of monthly debts
- Gift letters if any down payment funds come from family
The Consumer Financial Protection Bureau explains the home buying steps and what lenders review in its Owning a Home resources. On credit, scoring models generally treat several mortgage inquiries made within a short shopping window as a single inquiry. The length of that window depends on the scoring model, so confirm the current guidance on consumerfinance.gov before you apply to several lenders.
Loan size also shapes your paperwork. For 2026, the FHFA baseline conforming loan limit for one-unit properties is $832,750, and higher ceilings apply in designated high-cost areas such as Northern Virginia. Check your county on the FHFA conforming loan limit page, because a loan above the limit changes the documentation and pricing you should expect. For current benchmark rates, see the Freddie Mac Primary Mortgage Market Survey, and treat any figure as accurate only as of its publication date.
1. Grand Rates by Duane Buziak
Grand Rates by Duane Buziak is an independent mortgage consultation and rate comparison service for buyers who want help organizing their pre-approval file and seeing pricing from more than one source. Duane Buziak is licensed as a mortgage broker and lender, and he is not tied to a single lender.
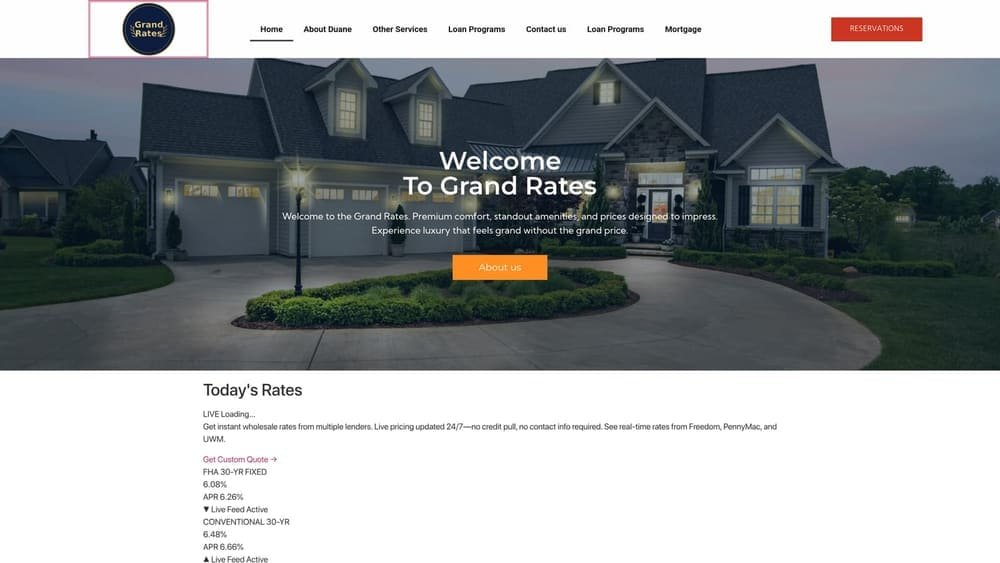
What sets it apart on this list is the order of operations. Pricing is compared across hundreds of wholesale lenders before any hard credit pull, so you see where your numbers land before a credit inquiry is on your report. Every other tool here is a single lender, so none of them can show you a competing lender’s price.
- Pre-approval document guidance tells you which items your situation needs, such as business returns, gift letters, or rental income paperwork, before you start uploading.
- Rate comparison with no credit hit lets you test scenarios without adding inquiries.
- Home loan consulting covers loan program fit, down payment strategy, and how debts affect your ratio.
- Independence from any one lender means the recommendation follows your file, not a lender’s product shelf.
- The service is free to the borrower.
The process is consultative. You work with a person, which suits buyers with self-employment income, multiple income sources, or a complicated down payment. It is not a self-serve app where you finish everything alone at midnight. Duane is licensed in VA, FL, TN, GA, DC, NC, SC, and MD, so buyers elsewhere will need a different option. Setup is light: a conversation, then document collection against a checklist built for your file. Duane Buziak runs the process day to day, and lenders in the wholesale network handle the underwriting once you choose one.
Pricing: free to the borrower, with no fee for the comparison or the consultation.
Best for: Buyers who want independent guidance and rate comparison before committing.
2. Rocket
Rocket is a large online lender built around a digital application, which makes it the most app-driven pre-approval workflow on this list. You enter income, assets, and debts, upload documents, and receive a pre-approval letter without needing to meet anyone.
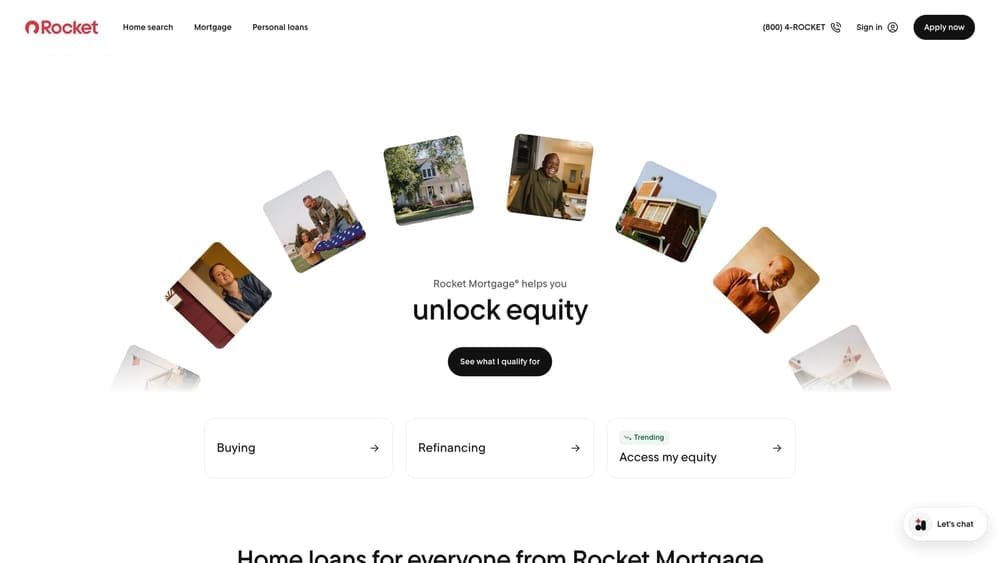
Its distinct strength is speed and self-service. Where other tools here pair a person with an online portal, Rocket is designed so you can complete most of the process on your own schedule.
- The online application collects your details in one place and walks you through what is missing.
- Digital document upload lets you send pay stubs and statements from your phone.
- Automated income and asset verification can pull data from your financial institutions, which may reduce the paper you hand over. Confirm current availability with Rocket.
- A pre-approval letter you can use when making offers.
- Multiple loan programs, so you can see more than one structure.
Rocket integrates with financial institution data connections for that verification step, and setup is handled by you, usually in a single sitting if your documents are ready. The limits are structural. It is a single lender, so there is no side-by-side comparison with other lenders’ pricing. Buyers with unusual income, such as multiple businesses or irregular commissions, may want a person to review the file before submitting, and the app-first model gives you fewer natural moments to ask questions.
Pricing: there is no upfront cost to apply. Your rate and fees depend on credit, down payment, property type, loan program, and market conditions, and Rocket’s website and your Loan Estimate are where to confirm them. Review the credit pull terms before you start so you know when the hard inquiry happens.
Best for: Buyers who want a fast, fully online approval.
3. Veterans United
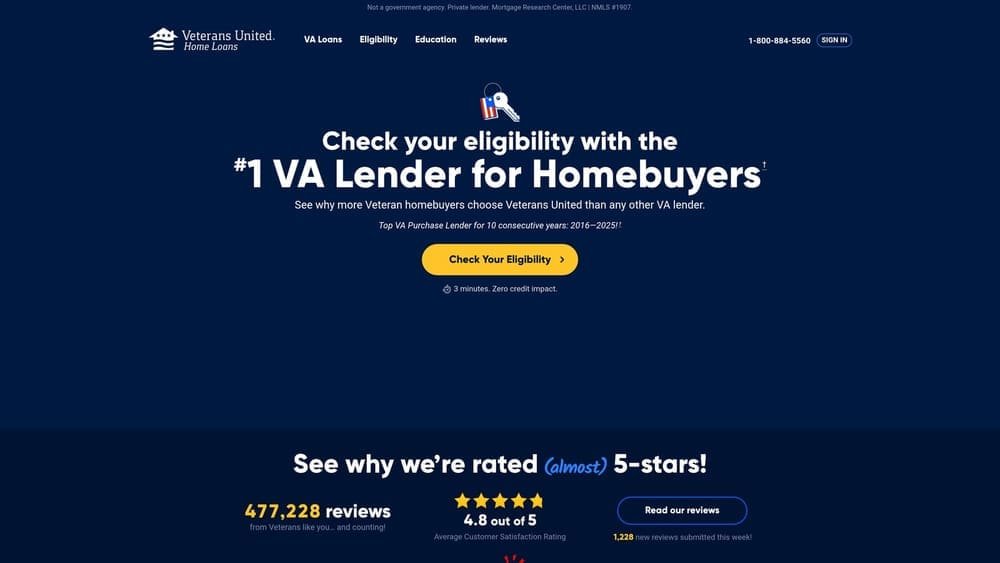
Veterans United is a lender focused on VA loans, so the checklist it supports differs from a conventional file. The most useful difference is help with the Certificate of Eligibility, the document that proves entitlement and is a prerequisite many buyers do not know how to obtain.
Where it stands out
Specialization is the draw. A team that handles VA files all day knows what a service-related document request looks like and how to explain it, which makes the checklist more precise for eligible buyers than a generalist’s would be.
- VA loan specialization means the checklist reflects VA-specific paperwork, not a generic list.
- Certificate of Eligibility support helps you secure the document that unlocks the benefit.
- An online document portal gives you one place to upload and track what you have sent.
- A dedicated loan team gives you named people to contact instead of a general queue.
What to weigh
This is a tool for VA-eligible buyers. If you are not a veteran, service member, or eligible surviving spouse, the main advantage does not apply, and you should confirm whether the lender offers other programs that suit you. It is also a single lender, so you will see its pricing only, not a comparison. Compare its Loan Estimate against at least one other source before you commit, as you would with any lender.
Integrations and setup details are on the company’s website. In practice you work through the online portal with your assigned team, who run the file day to day. Expect to supply the standard income, asset, and employment documents in addition to eligibility paperwork.
Pricing: not published as a flat figure on a comparison basis. Rates and costs depend on your credit, down payment, and market conditions, so request a Loan Estimate and see the company’s website for current terms.
Best for: Veterans and service members buying with a VA loan.
4. Movement
Movement is a national lender that pairs a loan officer with an online application and document portal. The model suits buyers who like a person on the phone but do not want to mail or fax paperwork.
Compared with the rest of the list, its distinctive trait is that mix. Rocket leans digital, Guild leans local and in person, and Movement sits between them: you submit documents online while a loan officer reviews the file and explains the next steps.
- The online application lets you start from home and avoid repeating information on paper forms.
- The document portal keeps pay stubs, bank statements, and tax returns in one secure place.
- Loan officer guidance means someone can tell you which documents your file needs and why.
- Multiple loan programs may be available, though you should confirm which ones apply in your state and price range.
Setup is straightforward: apply online, get matched with a loan officer, then work through the document list together. Details on integrations are on the company’s website. You and your loan officer share the day-to-day work, with the portal handling the uploads.
The limitation is the one that applies to every single lender here. You are looking at one company’s pricing, so there is no independent comparison built into the process. If you want to know whether a quote is competitive, you will need to gather a second quote on your own, ideally within a short shopping window so the credit inquiries are treated together under common scoring models.
Because the loan officer drives the experience, quality can depend on the individual you are paired with. Ask how often they will update you and what the expected timeline is from complete documents to a pre-approval letter.
Pricing: see Movement’s website for current information. Rates and fees depend on credit, down payment, property, and loan program, and a Loan Estimate shows the actual numbers for your file.
Best for: Buyers who want a loan officer plus online convenience.
5. Guild Mortgage
Guild Mortgage combines a local branch network with digital application tools, and it is the in-person option on this list. If you want to sit across a desk with a loan officer and a folder of printed statements, it is the one built for that.
That face-to-face support is the standout. Questions like “does this deposit need a letter of explanation?” are often easier to settle in a short meeting than in a message thread, particularly for first-time buyers.
- Local loan officers know the market, area property types, and common closing practices where you are buying.
- A digital application lets you begin online before you meet anyone.
- Document upload means you can send items in advance and bring only what is missing to the meeting.
- Multiple loan programs may be available. Confirm the specifics for your state and loan size.
Setup typically means applying online or contacting a branch, then working with the assigned loan officer. Integration details are on the company’s website. The loan officer and processing staff run the file day to day, while you handle uploads and signatures.
The limitations are worth stating plainly. Experience varies by branch and by loan officer, so two buyers can have different outcomes. Availability varies by state, and you should confirm that your state and loan type are supported before investing time. As a single lender, Guild gives you its own pricing and no side-by-side comparison. A buyer who values the in-person relationship may accept that, but one focused mostly on price should plan on getting a second quote.
Pricing: see Guild’s website for current information. Cost depends on credit, down payment, loan program, and property, and the Loan Estimate you receive after applying is the document to compare.
Best for: Buyers who prefer face-to-face help with their checklist.
6. NFM Lending
NFM Lending offers a loan officer-driven process with online application and document submission. The experience centers on one relationship, a single loan officer who stays with your file from first call to closing.
That continuity is what distinguishes it here. A dedicated loan officer can learn your timeline, remember that your bonus income needs a two-year history, and flag problems before the underwriter does.
- The online application gets your information in without a branch visit.
- Secure document submission keeps sensitive files out of email. Confirm the current portal details with the lender.
- Loan officer support gives you a person to ask when a request on the checklist is unclear.
- A range of loan programs may be available. Verify which ones fit your down payment and credit profile.
Setup is a mix of an online application and early calls with your loan officer. Integration details are on the company’s website. The loan officer coordinates day to day, with processing and underwriting teams behind the scenes.
The limits mirror the other single-lender options. You see one company’s pricing, not a comparison across lenders, and you should confirm state availability before you apply, since licensing varies. Program breadth should be verified for your specific scenario rather than assumed. Because the experience depends on the officer assigned, ask about their volume, response times, and how they handle surprises such as a late-arriving gift letter.
Pricing: see NFM Lending’s website. Rates and fees move with credit, down payment, loan program, and property type, so use the Loan Estimate to compare against another quote.
Best for: Buyers who want a dedicated loan officer relationship.
Ten Questions Buyers Ask About Pre-Approval
What documents do I need for a mortgage pre-approval?
Plan on a government ID, two years of W-2s and tax returns, about 30 days of pay stubs, two months of bank statements, employment and debt details, and gift letters if relevant. Self-employed buyers usually add business returns and a profit and loss statement.
What is the difference between pre-qualification and pre-approval?
Pre-qualification is an estimate based on information you provide. Pre-approval involves verified documents and a credit report, so it carries more weight with sellers and agents.
Does pre-approval hurt my credit score?
A pre-approval usually involves a hard inquiry, which can cause a small, temporary dip. Comparing rates through a service that does not pull credit first, such as Grand Rates by Duane Buziak, lets you see pricing before that inquiry.
Do multiple lender inquiries hurt my score?
Scoring models generally group mortgage inquiries made within a short window as one. The length varies by model, so check the current guidance at consumerfinance.gov.
Is pre-approval a guarantee of a loan?
No. It is not a loan commitment. Approval still depends on the appraisal, title, and your finances staying the same through closing.
How long does a pre-approval last?
Letters commonly stay valid for 60 to 90 days, though it varies by lender. If yours expires, you may need to refresh documents and credit.
Can I get pre-approved if I am self-employed?
Yes, but expect more paperwork, typically two years of personal and business returns plus a year-to-date profit and loss statement. A consultant who knows how different lenders treat self-employment income can help you present the file.
What credit score do I need for pre-approval?
Requirements depend on the loan program and lender. Many conventional loans look for a score of around 620 or higher, and a higher score generally improves pricing. A consultation can show where your score puts you.
Is it better to use one lender or compare several?
Comparison shows you whether a quote is competitive, which a single lender cannot do for you. The worked example above shows how a quarter-point difference adds up over five years.
Does it cost anything to get pre-approved?
Many lenders charge nothing to apply, though a credit report may be pulled and appraisal costs come later. Grand Rates by Duane Buziak is free to the borrower.
Matching a Pre-Approval Tool to Your Situation
Gather your documents before you contact anyone. A complete folder makes every option here faster and keeps you from reacting to a request at the last minute.
Duane Buziak recommends starting with the tool that matches how you want to shop:
- Independent comparison and checklist coaching: Grand Rates by Duane Buziak, particularly if your income or down payment is not straightforward.
- Fully digital, single-lender approval: Rocket, if you want to finish online.
- VA-eligible buyers: Veterans United, for its eligibility document support.
- Local or in-person support: Guild Mortgage, NFM Lending, or Movement, depending on whether you want a branch, a dedicated officer, or a loan officer paired with a portal.
Ready to secure a competitive mortgage rate for your Virginia home without impacting your credit score? Get your free personalized rate comparison from an independent consultant recognized as one of Virginia’s top loan officers, with no obligation and no hidden fees.



